Salar de Atacama, Chile · lithium brine evaporation pondsSentinel-2, 4 Sep 2026 · Contains modified Copernicus Sentinel data 2026
Data & intelligence · strategic minerals · rare earths

The data hub on strategic minerals and rare earths

mineral.watch is an independent data and intelligence portal. It cross-references verified official statistics on the mineral supply chains behind batteries, magnets, chips, grids and defence — who produces, who refines, who ships, and who depends on whom.

Then & now

Watch a supply chain being built

Drag the handle to compare satellite images of the same ground years apart.

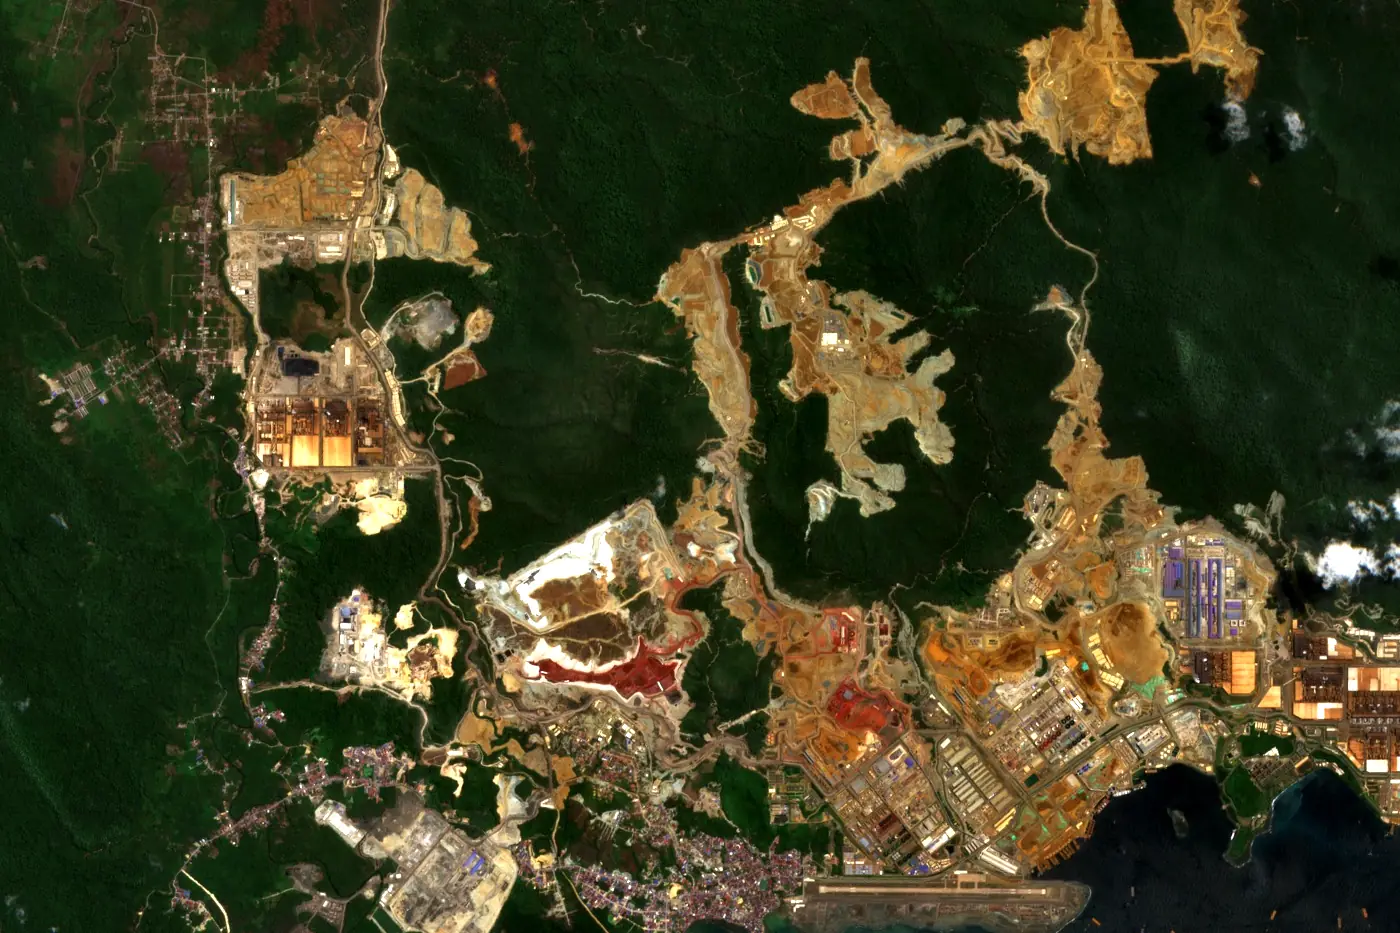
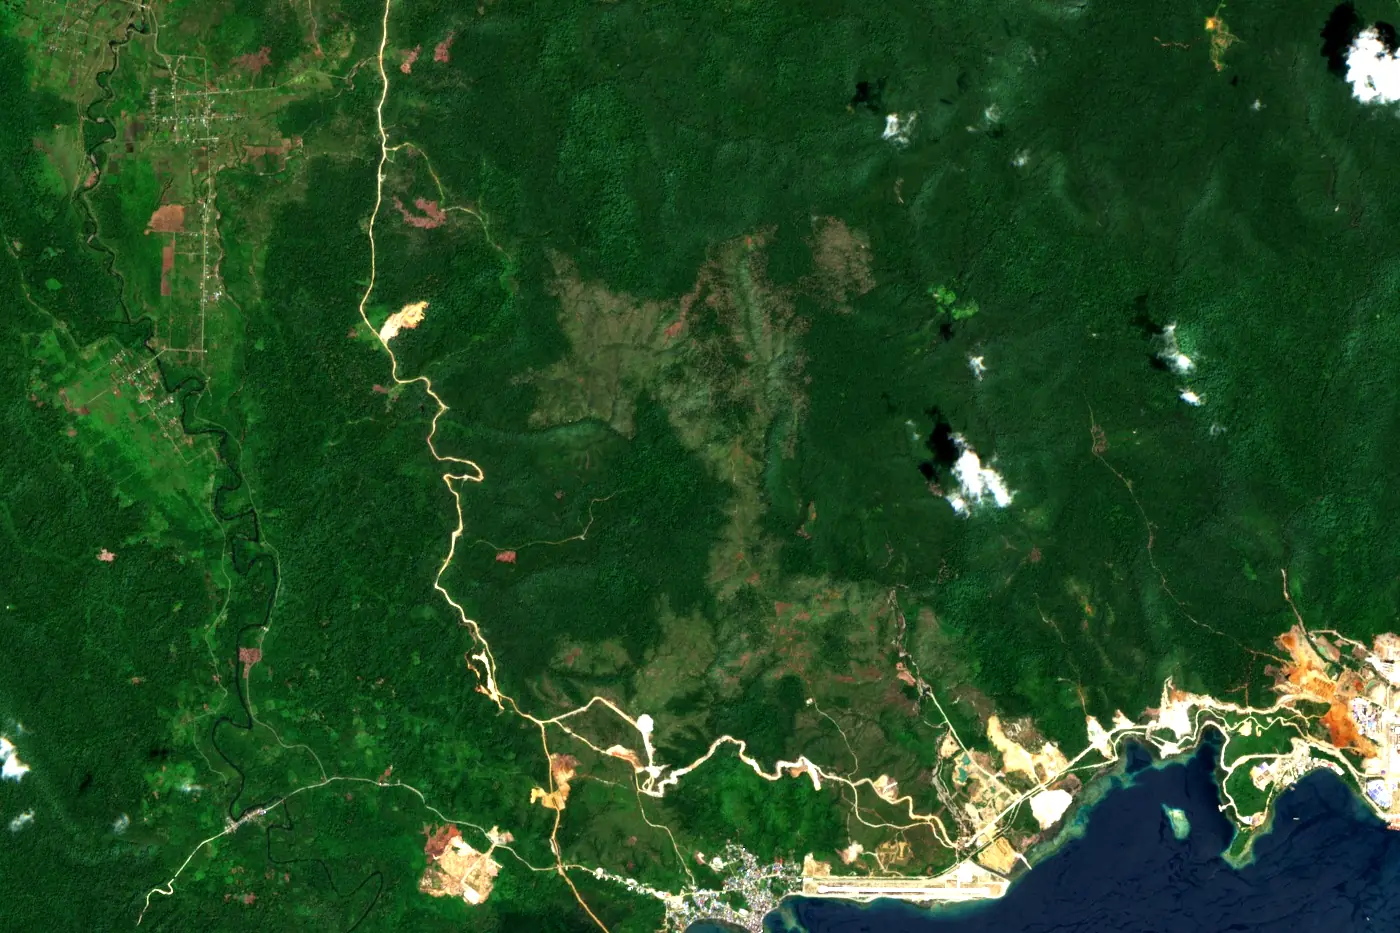
Sentinel-2 image of Weda Bay, Indonesia, 24 Aug 2026 Sentinel-2 image of Weda Bay, Indonesia, 12 Nov 2019 12 Nov 201924 Aug 2026

The same 14 km of Halmahera's coast, seven years apart. The tan scars are nickel laterite mines cut into rainforest; the grey grid on the shore is the Indonesia Weda Bay Industrial Park (IWIP), where the ore is smelted into nickel pig iron, matte and battery feed.
Sentinel-2 true colour, 12 Nov 2019 and 24 Aug 2026. Contains modified Copernicus Sentinel data 2019, 2026.

Nickel dashboard →
The minerals

One deep-dive per mineral

Each mineral gets its own data dashboard: production, reserves, trade flows, prices and supply-chain concentration. Graphite, rare earths, copper, uranium, lithium, manganese, cobalt, antimony, nickel, tin, tungsten, the chip metals gallium and germanium, the platinum-group metals, and tantalum and niobium are all live.

Live C

Graphite

The single largest material in a lithium-ion battery. Mining, spherical processing and anode production, mapped and charted.

Live Li

Lithium

The irreplaceable ion of the battery age: hard-rock and brine supply, China's conversion chokepoint and the boom-bust-boom price cycle — mapped and charted.

Live Co

Cobalt

The battery age's most concentrated bet: the DRC's mines and export quotas, China's refining grip and the race to design it out — mapped and charted.

Live Ni

Nickel

The stainless-age metal Indonesia cornered: two-thirds of mine supply, the class-1/class-2 divide, a broken benchmark and the quota machine — mapped and charted.

Live REE

Rare earths

Seventeen elements, one dominant refiner. Magnets, export controls and the race to diversify — mapped and charted.

Live Cu

Copper

The metal of electrification: grids, EVs, AI data centres, the smelting chokepoint and a looming supply gap — mapped and charted.

Live Mn

Manganese

The steel hardener turned battery metal: African and Australian mines, China's ~95% refining grip and the deep-sea nodule race — mapped and charted.

Live U

Uranium

The nuclear revival's fuel: mined on five continents, enriched by four companies — nearly half of it in Russia — mapped and charted.

Live Sb

Antimony

The small metal with outsized leverage: export bans, a fivefold price spike and a defence supply chain scrambling for sources — mapped and charted.

Live Sn

Tin

The solder in every circuit board: Myanmar's Wa State restart, Congo's Bisie under M23 pressure, Indonesia's crackdown and the 2026 price records — mapped and charted.

Live W

Tungsten

Armour, penetrators and every carbide cutting tool: China's export controls and 79% grip on mine supply, Japan's cut-off, the ninefold price shock and the Western rebuild — mapped and charted.

Live Ga·Ge

Gallium & germanium

The chip metals China banned outright: byproducts of alumina and zinc that no price signal can conjure — China's 99% grip on gallium, the US ban and its 27 November 2026 cliff, the two-tier price, and the radar, night-vision, fibre and AI power-electronics uses — mapped and charted.

Live Pt·Pd

Platinum group metals

The catalyst metals two countries mine four-fifths of: South Africa's 71% of platinum, Russia's 44% of palladium, the 2026 record and 44% slump, palladium's first surplus in 14 years, the Russian-duty fight and the exhaust, nitric-acid, glass and hydrogen uses — mapped and charted.

Live Ta·Nb

Tantalum & niobium

The capacitor metal and the steel metal: Congo and Rwanda's 68% of tantalum, the M23-held Rubaya mines and the coltan smuggled through Rwanda, the 2026 price spike, Brazil's 93% of niobium and the chip, jet-engine, rocket and pipeline uses — mapped and charted.

Why it matters

Small markets the whole economy runs on

Strategic minerals are tiny markets compared with oil or iron ore, but everything downstream depends on them. Concentration in mining and, above all, refining makes them a lever of industrial and geopolitical power. Africa shows the gap starkly: it mined about 77% of the world's cobalt in 2024 but refined under 2%, and 24% of its critical-mineral exports leave raw and 72% semi-processed (OECD, 2026).

Who produces what — share of world mine production, 2024
Top producers per mineral; ribbon width = that country's share of the mineral's world production.
PRODUCER MINERAL China → Graphite: 73.9% of world production (2024) China → Copper: 8.0% of world production (2024) China → Antimony: 42.8% of world production (2024) China → Rare earths: 74.9% of world production (2024) China → Tin: 25.1% of world production (2024) China → Tungsten: 77.8% of world production (2024) South Africa → Manganese: 36.9% of world production (2024) South Africa → PGMs: 56.9% of world production (2024) Indonesia → Cobalt: 11.8% of world production (2024) Indonesia → Nickel: 61.0% of world production (2024) Indonesia → Tin: 16.9% of world production (2024) DR Congo → Cobalt: 74.6% of world production (2024) DR Congo → Copper: 13.8% of world production (2024) Australia → Manganese: 12.4% of world production (2024) Australia → Uranium: 8.8% of world production (2024) Australia → Lithium: 62.2% of world production (2024) Russia → Nickel: 7.0% of world production (2024) Russia → Antimony: 14.3% of world production (2024) Russia → PGMs: 24.3% of world production (2024) Kazakhstan → Uranium: 37.3% of world production (2024) Canada → Uranium: 25.5% of world production (2024) Canada → PGMs: 5.2% of world production (2024) Chile → Copper: 24.0% of world production (2024) Chile → Lithium: 5.0% of world production (2024) Tajikistan → Antimony: 26.1% of world production (2024) Brazil → Lithium: 14.9% of world production (2024) Brazil → Tin: 9.4% of world production (2024) Peru → Copper: 11.9% of world production (2024) Peru → Tin: 11.0% of world production (2024) Zimbabwe → Lithium: 13.5% of world production (2024) Zimbabwe → PGMs: 8.6% of world production (2024) Gabon → Manganese: 13.3% of world production (2024) Myanmar → Rare earths: 12.3% of world production (2024) Namibia → Uranium: 11.7% of world production (2024) Ghana → Manganese: 9.4% of world production (2024) Philippines → Nickel: 9.3% of world production (2024) Madagascar → Graphite: 7.5% of world production (2024) USA → Rare earths: 7.5% of world production (2024) Vietnam → Tungsten: 7.1% of world production (2024) India → Graphite: 5.0% of world production (2024) Bolivia → Antimony: 4.6% of world production (2024) All other producers → Manganese: 28.0% of world production (2024) All other producers → Graphite: 13.7% of world production (2024) All other producers → Cobalt: 13.7% of world production (2024) All other producers → Nickel: 22.7% of world production (2024) All other producers → Copper: 42.2% of world production (2024) All other producers → Antimony: 12.3% of world production (2024) All other producers → Rare earths: 5.4% of world production (2024) All other producers → Uranium: 16.7% of world production (2024) All other producers → Lithium: 4.3% of world production (2024) All other producers → Tin: 37.6% of world production (2024) All other producers → Tungsten: 15.1% of world production (2024) All other producers → PGMs: 5.2% of world production (2024) China South Africa Indonesia DR Congo Australia Russia Kazakhstan Canada Chile Tajikistan Brazil Peru Zimbabwe Gabon Myanmar Namibia Ghana Philippines Madagascar USA Vietnam India Bolivia All others Manganese Graphite Cobalt Nickel Copper Antimony Rare earths Uranium Lithium Tin Tungsten PGMs PRODUCER MINERAL China → Graphite: 73.9% of world production (2024) China → Copper: 8.0% of world production (2024) China → Antimony: 42.8% of world production (2024) China → Rare earths: 74.9% of world production (2024) China → Tin: 25.1% of world production (2024) China → Tungsten: 77.8% of world production (2024) South Africa → Manganese: 36.9% of world production (2024) South Africa → PGMs: 56.9% of world production (2024) Indonesia → Cobalt: 11.8% of world production (2024) Indonesia → Nickel: 61.0% of world production (2024) Indonesia → Tin: 16.9% of world production (2024) DR Congo → Cobalt: 74.6% of world production (2024) DR Congo → Copper: 13.8% of world production (2024) Australia → Manganese: 12.4% of world production (2024) Australia → Uranium: 8.8% of world production (2024) Australia → Lithium: 62.2% of world production (2024) Russia → Nickel: 7.0% of world production (2024) Russia → Antimony: 14.3% of world production (2024) Russia → PGMs: 24.3% of world production (2024) Kazakhstan → Uranium: 37.3% of world production (2024) Canada → Uranium: 25.5% of world production (2024) Canada → PGMs: 5.2% of world production (2024) Chile → Copper: 24.0% of world production (2024) Chile → Lithium: 5.0% of world production (2024) Tajikistan → Antimony: 26.1% of world production (2024) Brazil → Lithium: 14.9% of world production (2024) Brazil → Tin: 9.4% of world production (2024) Peru → Copper: 11.9% of world production (2024) Peru → Tin: 11.0% of world production (2024) Zimbabwe → Lithium: 13.5% of world production (2024) Zimbabwe → PGMs: 8.6% of world production (2024) Gabon → Manganese: 13.3% of world production (2024) Myanmar → Rare earths: 12.3% of world production (2024) Namibia → Uranium: 11.7% of world production (2024) Ghana → Manganese: 9.4% of world production (2024) Philippines → Nickel: 9.3% of world production (2024) Madagascar → Graphite: 7.5% of world production (2024) USA → Rare earths: 7.5% of world production (2024) Vietnam → Tungsten: 7.1% of world production (2024) India → Graphite: 5.0% of world production (2024) Bolivia → Antimony: 4.6% of world production (2024) All other producers → Manganese: 28.0% of world production (2024) All other producers → Graphite: 13.7% of world production (2024) All other producers → Cobalt: 13.7% of world production (2024) All other producers → Nickel: 22.7% of world production (2024) All other producers → Copper: 42.2% of world production (2024) All other producers → Antimony: 12.3% of world production (2024) All other producers → Rare earths: 5.4% of world production (2024) All other producers → Uranium: 16.7% of world production (2024) All other producers → Lithium: 4.3% of world production (2024) All other producers → Tin: 37.6% of world production (2024) All other producers → Tungsten: 15.1% of world production (2024) All other producers → PGMs: 5.2% of world production (2024) China South Africa Indonesia DR Congo Australia Russia Kazakhstan Canada Chile Tajikistan Brazil Peru Zimbabwe Gabon Myanmar Namibia Ghana Philippines Madagascar USA Vietnam India Bolivia All others Manganese Graphite Cobalt Nickel Copper Antimony Rare earths Uranium Lithium Tin Tungsten PGMs
Source: BGS World Mineral Statistics, 2024 · Hover a ribbon for the exact share · Mineral names link to each dashboard
View the data behind this chart
MineralProducerShare of world mine production, 2024
ManganeseSouth Africa36.9%
Gabon13.3%
Australia12.4%
Ghana9.4%
All others28.0%
GraphiteChina73.9%
Madagascar7.5%
India5.0%
All others13.7%
CobaltDR Congo74.6%
Indonesia11.8%
All others13.7%
NickelIndonesia61.0%
Philippines9.3%
Russia7.0%
All others22.7%
CopperChile24.0%
DR Congo13.8%
Peru11.9%
China8.0%
All others42.2%
AntimonyChina42.8%
Tajikistan26.1%
Russia14.3%
Bolivia4.6%
All others12.3%
Rare earthsChina74.9%
Myanmar12.3%
USA7.5%
All others5.4%
UraniumKazakhstan37.3%
Canada25.5%
Namibia11.7%
Australia8.8%
All others16.7%
LithiumAustralia62.2%
Brazil14.9%
Zimbabwe13.5%
Chile5.0%
All others4.3%
TinChina25.1%
Indonesia16.9%
Peru11.0%
Brazil9.4%
All others37.6%
TungstenChina77.8%
Vietnam7.1%
All others15.1%
PGMsSouth Africa56.9%
Russia24.3%
Zimbabwe8.6%
Canada5.2%
All others5.2%
2×

Demand growth

The IEA projects demand for key battery minerals to roughly double or more by 2040 in its base scenarios, driven by EVs, storage and grids.

>70%

Refining concentration

For several critical minerals, a single country refines the large majority of world supply — a tighter chokepoint than mining itself.

50+

Critical mineral lists

The US, EU, Japan and others each maintain official critical-mineral lists; export controls and tariffs increasingly follow them.

Full access Opening soon

Free shows who mines it.
Full access shows who controls it.

The maps and production figures on every dashboard stay free. Full access opens the analysis that follows them on all fourteen dashboards, refreshed every month.

  • Mined vs refined
  • Refining & processing
  • Trade & prices
  • Export controls
  • The China chokepoint
  • Demand
  • Defence
  • Investment
  • Companies
China chokepoint · 9 minerals

Mined around the world, processed in China

China's share of world mining vs its share of the processing step after it

Sources: USGS, IEA, Cobalt Institute and industry estimates, as cited on each dashboard. The processing stage differs by mineral.

Trade · 6 dashboards

Ore flows in, refined metal flows out

Selected corridors into and out of China

Corridors as named on the cobalt, lithium, tin, rare-earth, manganese and gallium-germanium dashboards; arcs show direction, not tonnage. Germanium destinations: USGS, Jan–Sep 2025. Rare earths: USGS, US imports 2021–24.

All maps & dashboards

The complete version of everything on mineral.watch, refreshed every month.

Full access is opening soon. Join the waitlist and we'll email you when it does.

No payment now: we'll email you when full access opens. Buying for a team or an institution? Write to us.

What full access includes →
FAQ

Common questions

What is mineral.watch?

mineral.watch is an independent data and intelligence portal on strategic minerals and rare earths. It cross-references verified data from USGS, BGS, UN Comtrade, the IEA and the EIA to show who produces, refines, ships and depends on the materials behind batteries, magnets, chips, grids and defence systems. Each dashboard's maps and production figures are free; full access opens the analysis that follows.

Which minerals does mineral.watch cover?

Fourteen mineral dashboards are live — graphite, rare earths, copper, uranium, lithium, manganese, cobalt, antimony, nickel, tin, tungsten, the chip metals gallium and germanium, the platinum-group metals, and tantalum and niobium. The Mineral Explorer adds production and trade maps for 110 commodities from 1970 to 2024.

What is free, and what needs full access?

The opening sections of every dashboard are free: the world map, how the supply chain works and who produces what. So is the Mineral Explorer. Full access opens the analysis that follows them on all fourteen dashboards, from refining and trade to chokepoints, defence, investment and the companies, refreshed every month.

How do I get full access?

Full access to every map and dashboard opens soon. Join the waitlist and we'll email you when it opens; there is no payment now. For a team or an institution, write to hello@mineral.watch.

How much of the world's critical minerals come from Africa?

About a tenth by export value: Africa supplied 10.6% of world exports of raw and semi-processed minerals in 2023, some $266 billion, according to UNCTAD figures in the OECD's 2026 regional review (Critical minerals in Africa), and 24% of its critical-mineral exports leave raw and 72% semi-processed. For a few minerals it dominates mining: in 2024 Africa mined about 77% of the world's cobalt, 65% of its platinum-group metals, 63% of its manganese ore, 60% of its chromite and 35% of its bauxite (BGS). Refining is another story: it produced under 2% of the world's refined cobalt. With full access, the mined-vs-refined map on each mineral dashboard shows Africa's share at each stage.

What data sources does mineral.watch use?

Figures are cross-referenced from the USGS National Minerals Information Center, British Geological Survey World Mineral Statistics, UN Comtrade, the IEA and the EIA, plus industry bodies, price reporters and company reports where they hold the better number. Every chart is cited and dated on its page.

Is mineral.watch affiliated with any government or company?

No. mineral.watch is an independent project and holds no commercial position in the minerals or companies it covers.

Can I commission mineral.watch to produce a report?

Yes — the free sections of the dashboards are a sample of what we do. We take commissions for bespoke, source-cited work: supply-chain mapping from mine to refinery to end use, trade-flow and import-dependency analysis, country and commodity deep-dives, custom datasets and interactive dashboards like the ones on this site, and ongoing monitoring briefs for teams in policy, finance, industry and media. We also produce full written reports — charts, maps and citations included — ready for internal circulation or publication. Every deliverable is built on the same verified USGS, BGS, UN Comtrade and IEA data. Email hello@mineral.watch with a short note on the problem you're trying to solve and we'll come back with a scoped proposal.

Custom research

Need an ad hoc data-driven research report?

We produce bespoke, source-cited research on strategic minerals — supply-chain mapping, trade-flow analysis, country and commodity deep-dives, and policy briefs on producer-country rules such as Africa's export bans and processing plans — built on the same open, verifiable data behind this site.

Reach out at hello@mineral.watch
About

Introduce yourself and join the waitlist

mineral.watch is an independent data hub, and it grows with the people who use it. Introduce yourself and join the waitlist: we'll email you when full access opens, and let you know when new dashboards, datasets and research go live — no noise, just what's new.

Telling us your sector and organisation helps too: it shows us who relies on this data — analysts, policymakers, journalists, researchers — and shapes what we build next, from new minerals to custom research.

Prefer to talk directly? Corrections, data tips and collaboration ideas are always welcome.

Reach out to us

No payment now. We'll only use your details to tell you when full access opens and to send mineral.watch updates. No spam, unsubscribe anytime.